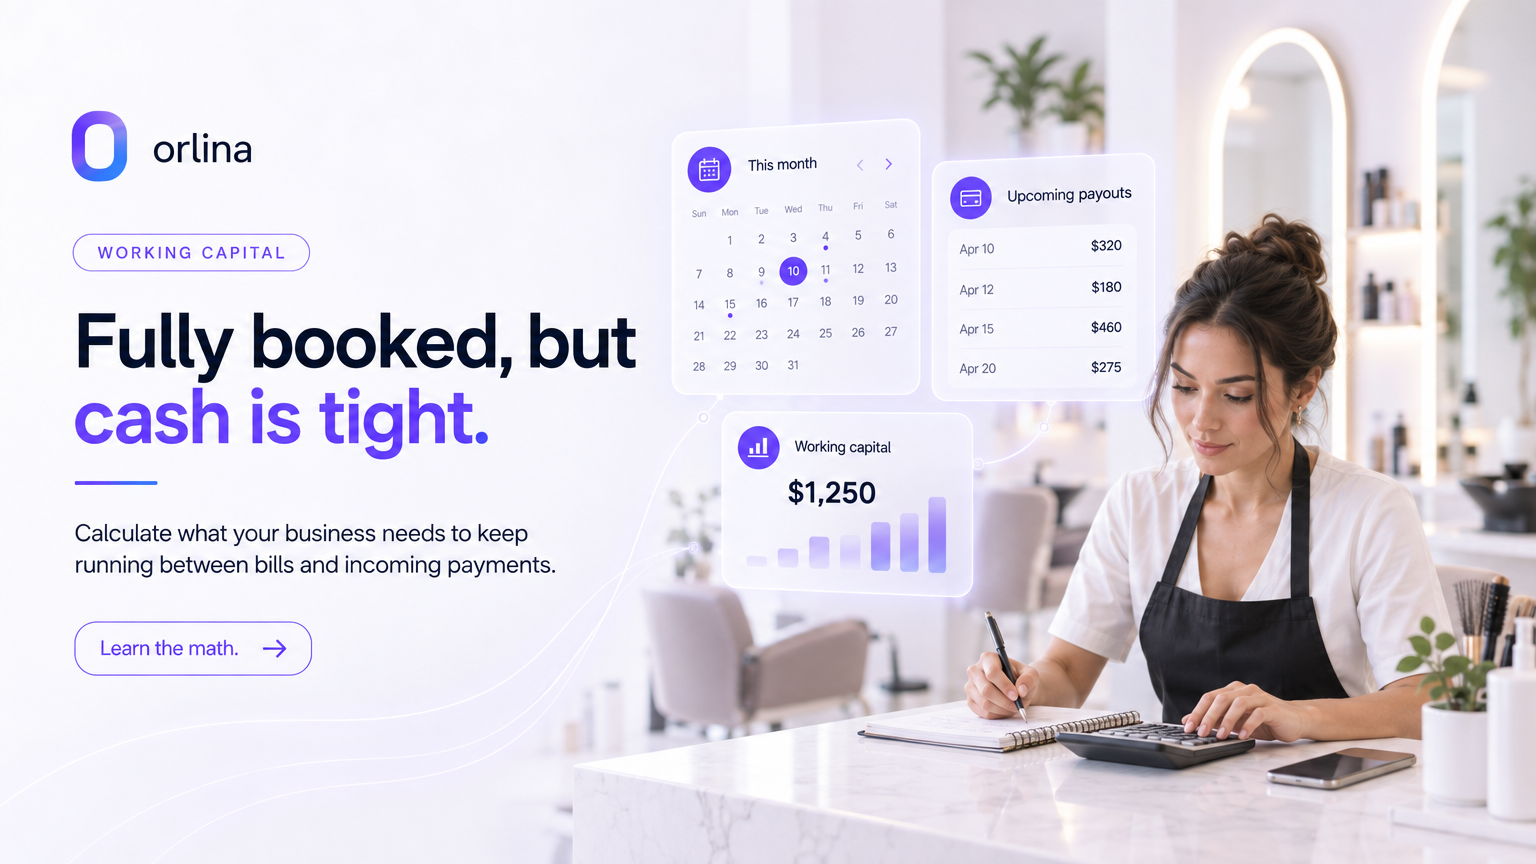
Working capital for beauty salons and barbershops is the essential financial reserve required to cover all operational costs while waiting for client payments to clear. According to financial management principles, a lack of liquid resources is a primary reason why small service businesses fail within their first few years. Maintaining control over this metric ensures you can pay rent, utilities, and suppliers on time, even if credit card payouts take days or weeks to reach your bank account.
What is Working Capital and Why is it Your Business's Oxygen?
Many beauty professionals make the classic mistake of confusing the cash entering the register today with the profit they can spend tomorrow. Working capital is, in simple terms, the money that "circulates" to keep the business structure functioning. If you perform a high-end hair coloring service today and the client pays via credit card, the cost of the bleach, water, electricity, and the professional's commission must be covered now, but the total funds might not hit your account for several business days.
The need for working capital arises specifically from this timing mismatch. In a salon or barbershop, you consume products and labor before or during the service delivery, but the financial cycle of receiving payment can be much longer. Without this resource, entrepreneurs fall into the dangerous cycle of "factoring" or "advancing" credit card receivables—paying high fees to banks just to access their own money—which quickly erodes profit margins.
Understanding this dynamic is fundamental for anyone wanting to move out of "survival mode." Many business owners believe their problem is a lack of clients when, in reality, they have a fully booked schedule but have lost control over their cash flow. Working capital isn't an "extra"; it is the foundation that allows you to open your doors every day without desperation.
The Crucial Difference Between Profit, Working Capital, and Emergency Funds
For professional financial management, it is mandatory to separate these three concepts. Mixing them is the shortest path to "silent bankruptcy," where the business looks busy, but the bills never seem to get paid.
- Profit: This is what remains after paying all expenses (fixed and variable) and provisions. Profit belongs to the business, and part of it can be distributed as owner's draw or reinvested.
- Working Capital: This is the amount dedicated to covering daily operational costs. It is not "yours" to spend; it belongs to the operation. If you withdraw working capital for personal use, you won't have money to restock shampoos or pay the electric bill next month.
- Emergency Fund: This is a value set aside for unpredictable and catastrophic situations, such as a central air conditioning failure or a sudden local economic shutdown. While working capital is used every month, the emergency fund is only touched in extreme cases.
Confusion occurs because, in daily life, all this money usually sits in the same bank account. Therefore, using digital management tools helps visualize what each value represents, preventing you from spending tomorrow's supplier payment on today's dinner.
Why a Full Book Doesn't Guarantee Cash in Your Pocket
This is the paradox of the beauty industry: you can serve 20 clients a day and still be in the red. This happens for three main reasons: payment processing delays, invisible variable costs, and the lack of upfront payments.
When you use card readers or online payment processors, the money isn't always instantaneous. If your salon generates $10,000 monthly, but 80% of that is on credit, you might only see that total value in staggered payouts. However, your rent is due on the 1st. If you don't have working capital, you can't pay the rent, even though you "sold" a lot of services.
Additionally, there is the cost of inventory replacement. Every service performed consumes a fraction of your products. If you don't account for this correctly when adjusting your prices, the money coming in barely covers the cost of the product used, leaving nothing for the "turnover," let alone profit. The result is a business that works hard but never prospers.
How to Calculate Your Working Capital Requirement (WCR)
Calculating working capital doesn't have to be a nightmare. Basically, you need to look at your Financial Cycle. The financial cycle is the time between paying your supplier and receiving payment from your client.
To calculate, follow these steps:
- List your fixed expenses: Rent, utilities, internet, scheduling systems, and your own salary.
- Calculate your variable costs: Backbar products (shampoos, dyes, disposables) and staff commissions.
- Analyze average collection period: How long does it take, on average, for sales money to hit your account?
- Analyze average payment period: How much time do you have to pay your suppliers?
Simplified Formula:
Working Capital Requirement = Accounts Receivable + Inventory Value - Accounts Payable.
If the result is a high positive number, it means you need a lot of cash sitting idle just to keep the business from stopping. If it is low, your business is financially healthy and sustains itself with its own flow.
| Component | Salon A (Poor Health) | Salon B (Good Health) |
|---|---|---|
| Payment Receipt | 14-30 days (Credit/Delayed) | 1-2 days (Debit/Instant) |
| Inventory | 60 days (Overstocking) | 15 days (Just-in-time) |
| Supplier Payment | Upfront (at purchase) | 30 days (Net-30 terms) |
| Capital Need | Very High | Very Low |
As seen in the table, Salon B has much better financial health because they receive money quickly and pay suppliers slowly, while Salon A is always "chasing its tail."
Practical Example: The Case of John’s Barbershop
John owns a barbershop that grosses $15,000 per month. His fixed expenses total $5,000. He spends $2,000 on products and $4,500 on commissions for two other barbers.
John’s problem is that he buys all his stock at once for 3 months (investing $6,000 in one go) and his clients mostly pay with credit cards that have a long clearing period.
- Immediate bills to pay: Rent ($2,000), Utilities ($500), Commissions ($4,500) = $7,000.
- Cash on hand on the 5th: $3,000 (leftover from last month).
- Result: John has a $4,000 hole. He will need a loan or to pay high fees to advance his card sales, losing money on interest.
If John had calculated his working capital, he would know he needs at least $10,000 in an operational reserve to handle these thirty days of mismatch without resorting to banks.
Strategies to Reduce Working Capital Needs
You don't necessarily need "more money" to solve the problem; sometimes, you need "better processes." Here are four pillars to reduce the pressure on your cash flow:
1. Encourage Instant Payments
Every dollar that enters your account instantly is a dollar you don't need to pull from your working capital. Consider offering a small perk or a simple add-on service for those who pay via instant transfer methods or debit. Using a professional online scheduling system allows you to track these entries accurately. This improves your immediate cash flow and helps in reducing no-shows.
2. Smart Inventory Management
Idle inventory is money losing value. Many salon owners get swayed by supplier promotions: "Buy 12, pay for 10." If those 12 products take 6 months to be used, you've locked your cash on a shelf. Prefer buying smaller quantities more frequently, keeping the cash in your account for other priorities. Learn more about choosing cosmetic suppliers strategically.
3. Negotiate Terms with Suppliers
Always try to match your payment terms with your collection terms. If credit card processors pay you in 7 days, try to pay your color supplier in 15 or 30 days. This "breathing room" is what allows the client's money to arrive before you have to pay for the goods. Effective supplier management is vital for any small business owner.
4. Plan Your Withdrawals (Owner's Draw)
The most common mistake is the owner "robbing" the business register whenever a personal bill comes up. Define a fixed monthly withdrawal amount. If the salon had an excellent month, don't increase your withdrawal immediately; use that surplus to strengthen your working capital. This will provide security for low-season months.
The Role of Technology in Financial Health
Keeping track of all this in a notebook or spreadsheet can become confusing and prone to errors. A modern online scheduling system helps not only with organizing times but with financial predictability.
With Orlina, you have access to a performance dashboard that shows your real revenue. Furthermore, the AI assistant Gabriel helps keep the schedule full through automated client engagement, ensuring a constant flow of incoming cash.
When you automate the booking process, you free up time for what really matters: analyzing the numbers and managing the business. Knowing exactly how many services are booked for next week allows you to predict how much product will be needed and how much money will come in, facilitating the calculation of your turnover.
Risks of Not Having Working Capital
Ignoring the need for working capital puts your salon or barbershop in a constant risk zone. The main dangers include:
- Bank Debt: Frequent use of overdrafts or high-interest short-term loans.
- Loss of Credit with Suppliers: Delaying payments generates late fees and can cut off your supply of essential products.
- Inability to Grow: Without cash on hand, you can't invest in a new course, a better chair, or marketing to attract more clients.
- Emotional Stress: Uncertainty about whether there will be money to pay staff at the end of the month consumes the entrepreneur's mental health.
Checklist to Start Your Working Capital Reserve Today
If you realized your business is operating without working capital, don't panic. It is possible to build this reserve gradually:
- Separate Accounts: Have one bank account for the business and another for yourself. Never mix them.
- Set a Goal: Ideally, have between 3 to 6 months of fixed costs saved just for working capital.
- Reduce Unnecessary Costs: Analyze waste, such as excessive energy bills or water waste.
- Use Technology to Your Advantage: Implement digital tools to ensure organized entries and avoid gaps in the schedule.
Building working capital requires discipline, but it is what separates amateurs from successful entrepreneurs in the beauty sector. When money stops being a daily worry, you gain the freedom to focus on the quality of your service and customer care.
Conclusion
Managing a beauty salon or barbershop goes far beyond mastering the technique of cutting or coloring. Financial management, specifically mastering working capital, is what guarantees the longevity of the business. By understanding that gross revenue is not profit and that there is a waiting period between the work performed and the available cash, you take control of your financial destiny.
Remember: the goal is not just to have a full schedule, but to have a profitable and secure business. Use tools like Orlina to professionalize your service and facilitate the management of your time and money. With organization, working capital will stop being a problem and become the security you need to grow.
Frequently asked questions
What is the ideal working capital amount for a beauty salon?
There is no fixed value, but the general recommendation is to have the equivalent of 3 to 4 months of all your fixed and variable costs combined in cash. This ensures that even in very slow months or with delays in card payments, you can honor commitments like rent, utilities, and suppliers without resorting to loans.
Is it better to advance card sales or take a loan for working capital?
Both options should be avoided as they carry interest that eats into your profit. However, advancing receivables usually has slightly lower rates than unsecured loans. The best solution is always planning: reduce expenses and increase instant payment entries (like debit or transfers) to build your own working capital without depending on banks.
How does an online scheduling system help my working capital?
An online scheduling system provides financial predictability. By seeing your upcoming week's appointments, you can forecast revenue and manage inventory more accurately. This prevents overspending on supplies and helps you understand exactly when cash will be entering your business.
Can I use my profit to form working capital?
Yes, this is the healthiest way to build your reserve. Instead of withdrawing all the month's profit as an owner's draw, you should allocate a percentage (for example, 20%) to build the company's working capital until it reaches the target value necessary for operational security.
Should working capital be kept in a financial investment?
Yes, it is recommended that working capital be kept in a high-yield savings account or a liquid investment that you can withdraw at any time. This way, the money doesn't lose value to inflation but remains accessible for when the salon or barbershop's bills come due throughout the month.