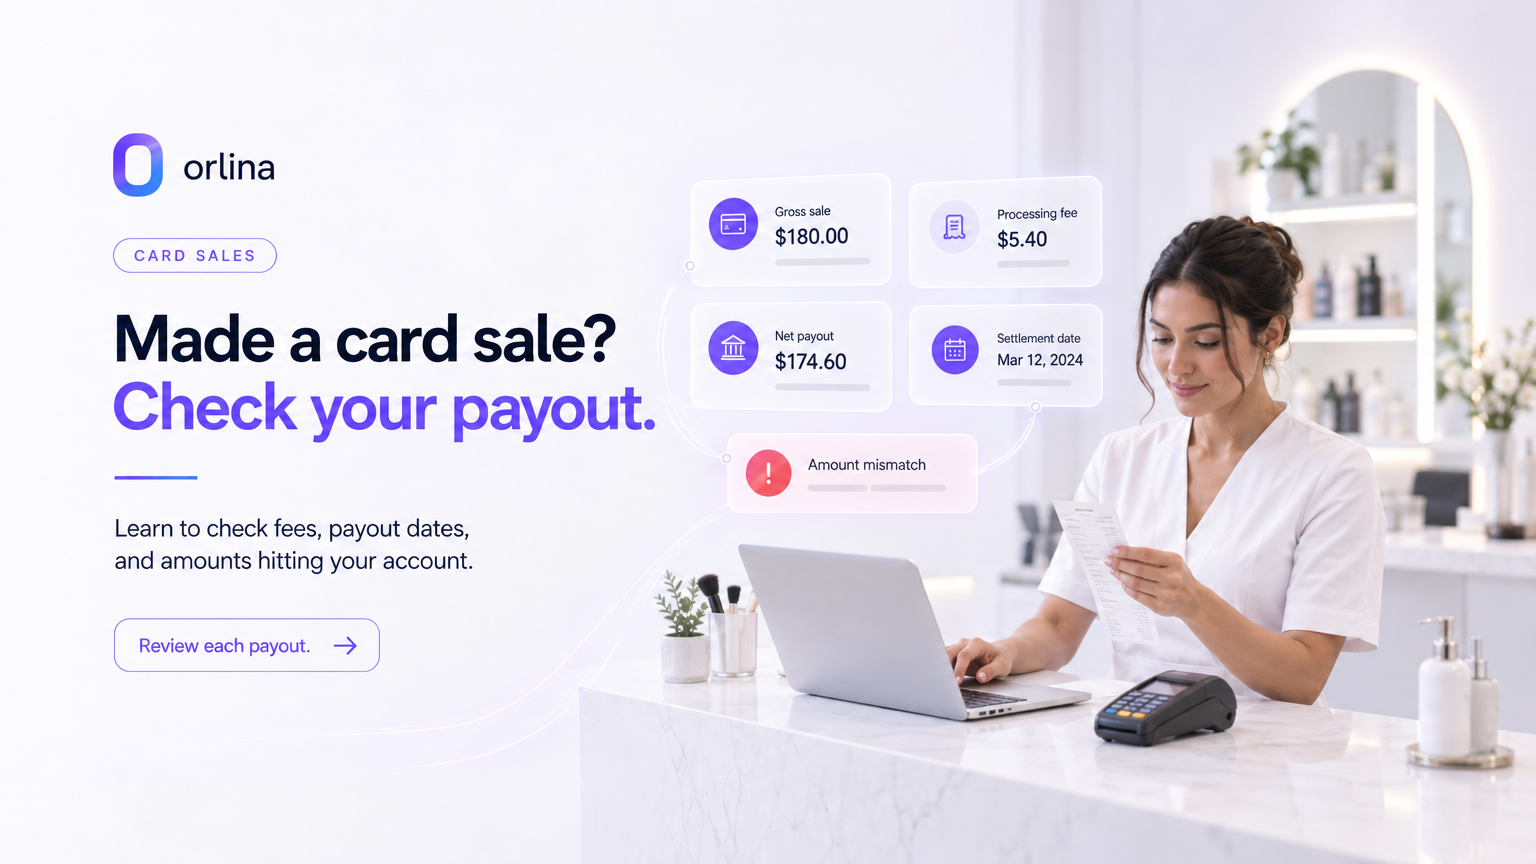
Credit card reconciliation for service professionals is the process of verifying that every sale made via a card reader or payment link was properly processed, correctly taxed, and deposited into your bank account within the agreed timeframe. Performing this rigorous check ensures you don't lose money to hidden fees, processor system glitches, or unidentified deposits, thereby maintaining your business's financial health. According to industry data, businesses can lose up to 3% of their revenue to payment processing errors if they don't perform regular audits.
For those in the beauty, wellness, or fitness sectors, handling multiple payment methods is daily routine. A client pays for a haircut, color service, or personal training session using a debit card, credit card, or digital wallet. By the end of the day, the bank balance never matches the gross sales total, and that is precisely where many professionals get lost. The lack of reconciliation is a major financial drain in small businesses, hiding errors that, when added up over a year, could represent the cost of new equipment or several months of rent.
The Importance of Payment Reconciliation for Solo Entrepreneurs
Many professionals assume that payment processors never make mistakes. However, technical failures, higher-than-contracted fee applications, and bank transfer delays are more common than imagined. For a solo entrepreneur or a small business owner, every dollar counts. Reconciliation is not just about "checking the money"; it’s about auditing your own contract with the merchant service provider.
When you fail to reconcile, you become vulnerable to three primary issues:
- Incorrect Fees: The processor might apply a 4.99% fee on a sale that should have been 3.99% based on your volume or tier.
- Unprocessed Sales: Due to a signal error in the card reader, the sale might show as "approved" on the paper receipt but never actually reaches the processor's system.
- Delayed Payouts: Funds that should have cleared in two business days take seven, causing you to pay overdraft interest because your cash flow is misaligned.
Implementing efficient digital management is the first step toward having the time to look at these numbers. Without an organized schedule, you can barely track what you sold, making reconciliation nearly impossible.
Differentiating Gross Value, Fees, and Net Value
The first step toward effective reconciliation is understanding the anatomy of a card sale. Many professionals make the mistake of looking only at the total amount the client paid, forgetting that this money passes through a "toll booth" before reaching the checking account.
Gross Value
This is the total price of the service provided. If your blowout costs $100 and the client pays by card, the gross value is $100. This is the amount that should appear in your appointment history and your calendar.
Processor Fees (MDR)
MDR stands for Merchant Discount Rate. It refers to the percentage the processor retains for each transaction. These fees vary drastically between debit cards, standard credit cards, and rewards cards (like Amex or premium Visa cards). Additionally, if you use "instant payouts" or "same-day funding," there is usually an extra percentage or flat fee attached.
Net Value
This is what remains for you. It is the gross value minus transaction fees and any processing surcharges. This is the exact amount you should verify against your bank statement.
Step-by-Step Manual Reconciliation Guide
While large corporations use complex automated reconciliation software, a small business owner can (and should) do this organized by following three pillars of comparison.
1. Save Your Receipts (Physical or Digital)
Whenever a sale is made, record the amount and the type (Debit, Credit, etc.). If you use Orlina, this record is centralized in your appointment history, making it immensely easier to search later.
2. Access Your Merchant Portal
At least once a week, log into your payment processor’s app or website (e.g., Square, Clover, or Stripe). There, you should pull a "Transaction Report." This report will show every swipe/dip, the fee applied, and the expected payout date.
3. Compare with Your Bank Statement
The final step is to cross-reference the processor's report with your business bank account statement. The net value indicated in the merchant portal must match the deposit in the bank exactly. If the processor says they deposited $95.50 for Monday’s sales, that exact amount should appear on your statement.
| Transaction Type | Gross Value | Example Fee | Estimated Net Value | Standard Payout Time |
|---|---|---|---|---|
| Debit Card | $100.00 | 1.5% + $0.10 | $98.40 | 1-2 Business Days |
| Credit Card | $100.00 | 2.9% + $0.30 | $96.80 | 2-3 Business Days |
| Instant Payout | $100.00 | 2.9% + 1.5% | $95.60 | Minutes/Same Day |
Understanding Instant Payouts and Payout Cycles
Payout cycles are the biggest challenge in reconciliation. When you run your business, you need to decide how you receive your funds:
- Standard Flow: You receive the net amount (minus fees) in batches every 24 to 48 hours.
- Instant Funding: You receive the money almost immediately (minus transaction fees AND an additional instant transfer fee).
Instant funding is a common trap for working capital. Often, the convenience fee is overlooked, which can turn a profitable service into a break-even one after all financial deductions. During reconciliation, you must verify if the total fees applied for the speed of the transfer match your expectations and contract terms.
Identifying Chargebacks and Cancellations
A chargeback occurs when a client disputes a charge with their card issuer, or when you cancel a sale due to an error.
In reconciliation, chargebacks appear as negative values. It is vital to monitor these because most processors charge an additional administrative fee (often $15 to $25) just to process the dispute. While professional liability insurance can help with legal disputes, daily financial reconciliation prevents you from providing a service and losing the payment due to an undetected or improper dispute.
Real-World Example: John’s Barbershop
To make this clear, let’s look at a day at John’s Barbershop. He uses a processor that charges 2.6% + $0.10 per transaction.
Sales for October 10:
- Client A: Haircut ($40.00) - Credit Card
- Client B: Beard & Haircut ($65.00) - Credit Card
- Client C: Hair Product ($25.00) - Credit Card
Reconciliation Calculation:
- Total Gross Sales: $40 + $65 + $25 = $130.00.
- Total Fees:
- Transaction fees: 3 transactions x $0.10 = $0.30.
- Percentage fees: $130.00 x 2.6% = $3.38.
- Total Fees: $3.68.
- Expected Net Payout: $130.00 - $3.68 = $126.32.
If on October 12, John sees a deposit of only $115.00, he knows there is an $11.32 discrepancy that needs to be questioned with the processor. Without this simple calculation, he might never notice the missing funds.
Weekly Review Checklist
To avoid getting lost in paperwork, follow this checklist every Friday or Monday:
- Total Sales: Export the total sales by payment method from your online scheduling system.
- Check Merchant Portal: Ensure the total sales recorded in the processor's system match what you marked in your calendar.
- Validate Fees: Pick 3 random sales and manually calculate the fee. Is the discount correct?
- Verify Deposits: Open your bank statement and mark each deposit from the processor. Does the net amount match the report?
- Check Pending Items: Are there any sales "in review" or "declined" that you thought were approved?
The Role of Organization in Financial Flow
Although card reconciliation is a purely financial process, it depends entirely on your operational organization. If you don't know who was treated, what the service was, and how the client paid, reconciliation becomes a nightmare.
This is where a robust online scheduling system makes the difference. By centralizing information for each appointment, you create a "source of truth." When you know exactly what happened in the salon or barbershop, confronting the card processor's data becomes a task of minutes, not hours.
Research from the Small Business Administration (SBA) suggests that meticulous financial tracking and reconciliation are among the most effective tools to prevent premature business failure, allowing for a clear view of real profit margins.
Handling Discrepancies: What to Do When Errors Are Found
If you identify that the processor did not deposit a value or charged an incorrect fee, the first step is to contact the merchant support with the Transaction ID or Authorization Code. These numbers are printed on the card reader receipt or found in the sale details in the app.
Never leave discrepancies to be resolved months later. Most processors have a limited window for disputes (usually 30 to 90 days). Discipline in reconciliation protects your assets.
Integrating AI for Better Control
Modern tools like Gabriel, Orlina’s AI assistant, help keep your schedule tight and your records accurate. When appointments are managed automatically, the data used for reconciliation is cleaner. Gabriel handles confirmations and reminders, reducing the "chaos" that leads to payment recording errors.
In the Pro plan ($49/month), Gabriel even provides a daily summary for the owner on WhatsApp, helping you stay on top of the day's expected revenue before you even open your bank app.
Conclusion
Credit card reconciliation is not an optional task for those who wish to grow sustainably. It is the only way to ensure that the fruit of your labor—the hours spent standing and serving clients—is fully respected by financial institutions.
By mastering the difference between gross and net value, understanding the weight of fees, and maintaining a review ritual, you take the reins of your business. Remember: what is not measured is not managed. Start your reconciliation today and discover where every cent of your company is going.
If you still spend too much time organizing your schedule manually and have no time left for finances, consider moving to a digital solution. Start free — your first 10 appointments at no cost with Orlina and see how organization can free up time for you to take care of what really matters: your profit and your art.
Frequently asked questions
What is a Transaction ID and why is it important for reconciliation?
A Transaction ID (or Authorization Code) is a unique string that identifies every single card transaction. It is fundamental in reconciliation because if there is a discrepancy or missing payment, this ID is what you will use to open a ticket with your processor to locate the sale. Without this code, it is extremely difficult to prove that a specific sale was performed but not paid.
Is instant funding worth the extra cost for a small business?
It depends on your cash flow needs. Instant funding turns future receivables into immediate cash, but it comes at a premium price (often an extra 1% to 1.5% on top of standard fees). Financial experts generally recommend using it only for emergencies or high-return investments, rather than covering recurring fixed costs, as it eats into your long-term profit margins.
How long should I keep physical credit card receipts?
Ideally, you should keep them for at least 90 days, which is the typical window for customers to contest a sale (chargeback). However, if you use a digital system that records the sale with all pertinent data (amount, date, type), the need for physical paper decreases. Most modern processors also store this data digitally for at least 12 to 24 months in their portals.
Why is the amount deposited in my account different from my total sales?
This difference occurs because of the deduction of processing fees (MDR) and potentially instant payout fees. Additionally, some processors deduct equipment rental fees or software subscriptions directly from your daily or weekly payouts. Reconciliation serves specifically to detail each of these deductions and ensure they align with your contract.
How do I reconcile high-volume days without getting confused?
The best way is to use a report from your processor that separates sales by "Transaction Date" and "Funding Date." For busy days, you might have one total sales figure but multiple smaller deposits if your processor batches transactions differently. Verify that the sum of the net deposits matches the gross sales minus the total fees. It is suggested to do this weekly to ensure your bank statement aligns with your appointment calendar.